Renovation Loans
A renovation loan lets you finance the purchase or refinance of a home and the cost of renovations with one convenient loan. Whether you're buying a fixer-upper or upgrading your current home, programs such as the FHA 203(k) and Fannie Mae HomeStyle renovation loan roll home improvement costs into your mortgage, simplifying the process and helping you create the home you've always envisioned.
- One loan, one payment
- FHA 203(k) and HomeStyle
- Buy or refinance
The basics
What is a renovation loan?
A renovation loan is a single mortgage that covers both the cost of buying or refinancing a home and the funds needed for repairs and home improvements. Options include the FHA 203(k) (Limited or Standard) and the Fannie Mae HomeStyle renovation loan. Instead of juggling multiple loans, you make one monthly mortgage payment.
- Covers
- Home + repairs
- Programs
- FHA 203(k), HomeStyle
- Use for
- Purchase or refinance
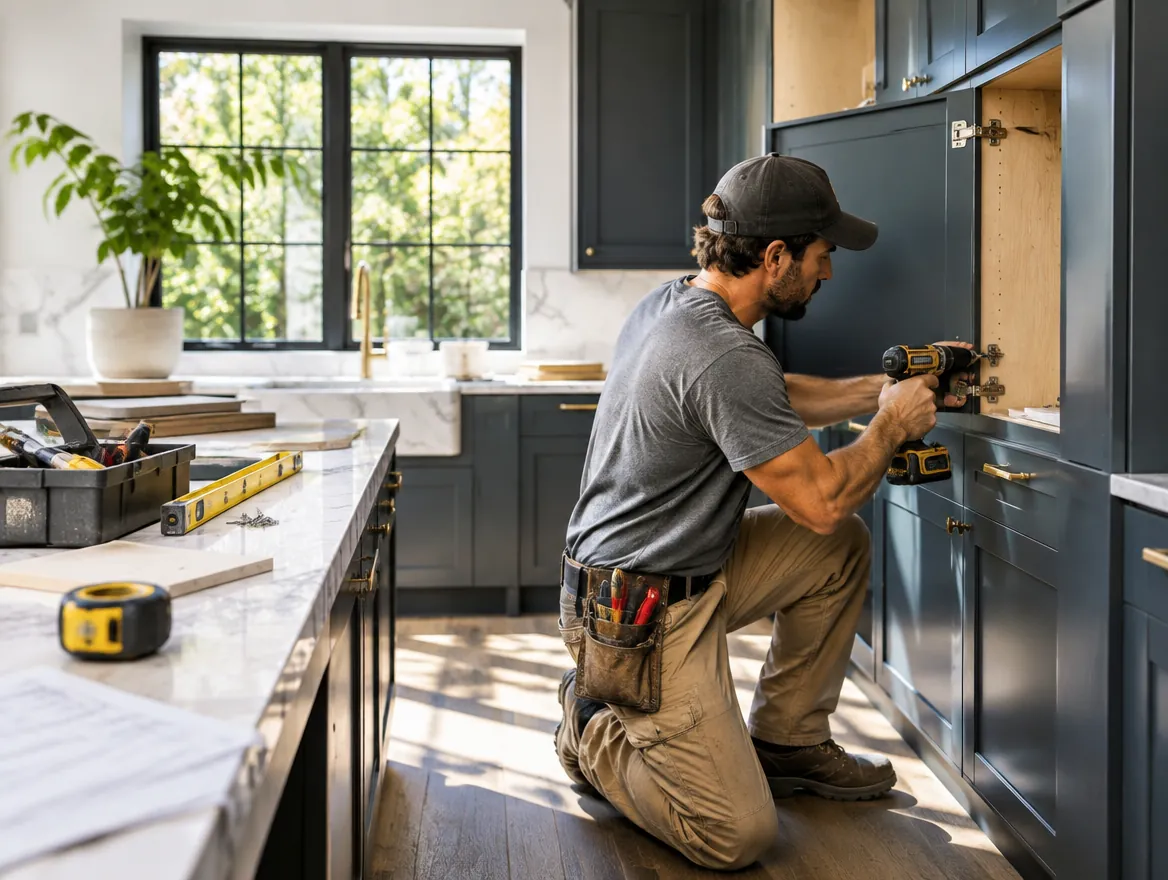
How it works
Your renovation loan in four steps
Buying a fixer-upper or improving the home you have, you work with one licensed loan officer from first call to final draw.
- 01
Get pre-approved
Share your income, assets and credit. Your loan officer helps you compare FHA 203(k), HomeStyle and other renovation options.
- 02
Plan the work
Choose a qualified contractor and gather detailed bids. The scope and cost of the project help set your loan amount.
- 03
Appraisal and underwriting
An appraiser estimates the home's value after improvements, and the lender reviews your file and the renovation plan.
- 04
Close and renovate
Sign your loan documents. Renovation funds are typically held in escrow and released in draws as work is completed.
From contractor bids to final draw
One licensed loan officer guides each step
Conventional option
HomeStyle renovation loan
The Fannie Mae HomeStyle renovation loan lets you finance the purchase or refinance of a home and the cost of renovations in a single conventional loan. It's a strong option for buying a fixer-upper or making home improvements to your current home, combining your mortgage and renovation costs into one loan with one monthly payment. At HomyLoan, we guide you through every step, from contractor bids to final draw.
Upgrades, not just repairs
HomeStyle can cover a wide range of improvements, from essential repairs to kitchens, baths and additions.
More property types
Available for a primary residence, and in some cases a second home or eligible investment property.
Contractor bids and draws
Your contractor's bids set the budget. Renovation funds are typically held in escrow and paid out in draws as work is completed.

Homy is online
Ask Homy anything about home loans
Hi, it's Homy! I can explain loan programs, down payments and the steps to buy or refinance in Texas. For advice on your situation, a licensed loan officer is one tap away.
Homy gives general information, not a loan offer or approval. HomyLoan, LLC is a licensed mortgage broker, NMLS 2783307.
 HomyHomyLoan assistant
Homy is an automated assistant, not a loan officer, and answers are general information. Please don't share your Social Security number or account numbers in chat. How chat data is used
Renovation loan FAQs
A renovation loan combines the cost of buying or refinancing a home with the cost of repairs or improvements in one mortgage. Common options include the FHA 203(k) and Fannie Mae HomeStyle loans.
FHA 203(k) is government-insured and follows FHA rules, including mortgage insurance and a primary residence requirement. HomeStyle is a conventional option that may also be used for some second homes and investment properties.
Renovation funds are typically held in escrow and released in draws to the contractor as work is completed and inspected.
The lender usually uses the home's appraised value after the planned improvements, along with your contractor's bids, to set the loan amount within program limits.
Usually not. Most renovation programs require a qualified, licensed contractor, though limited exceptions may exist depending on the program and the lender.
Yes. Many renovation programs can be used to refinance the home you already own and fund improvements in the same loan.